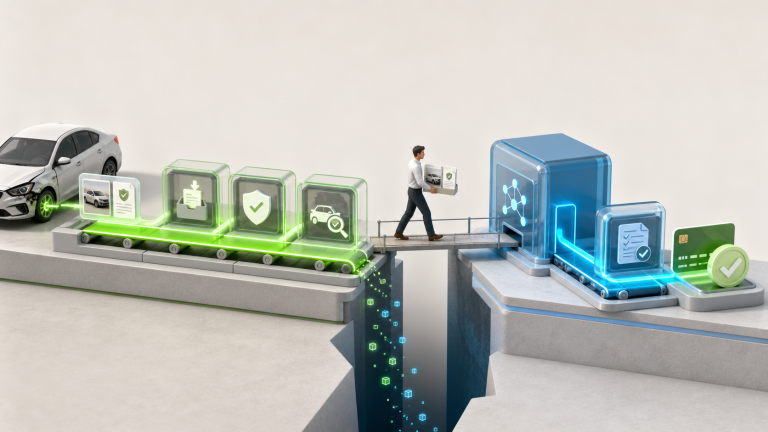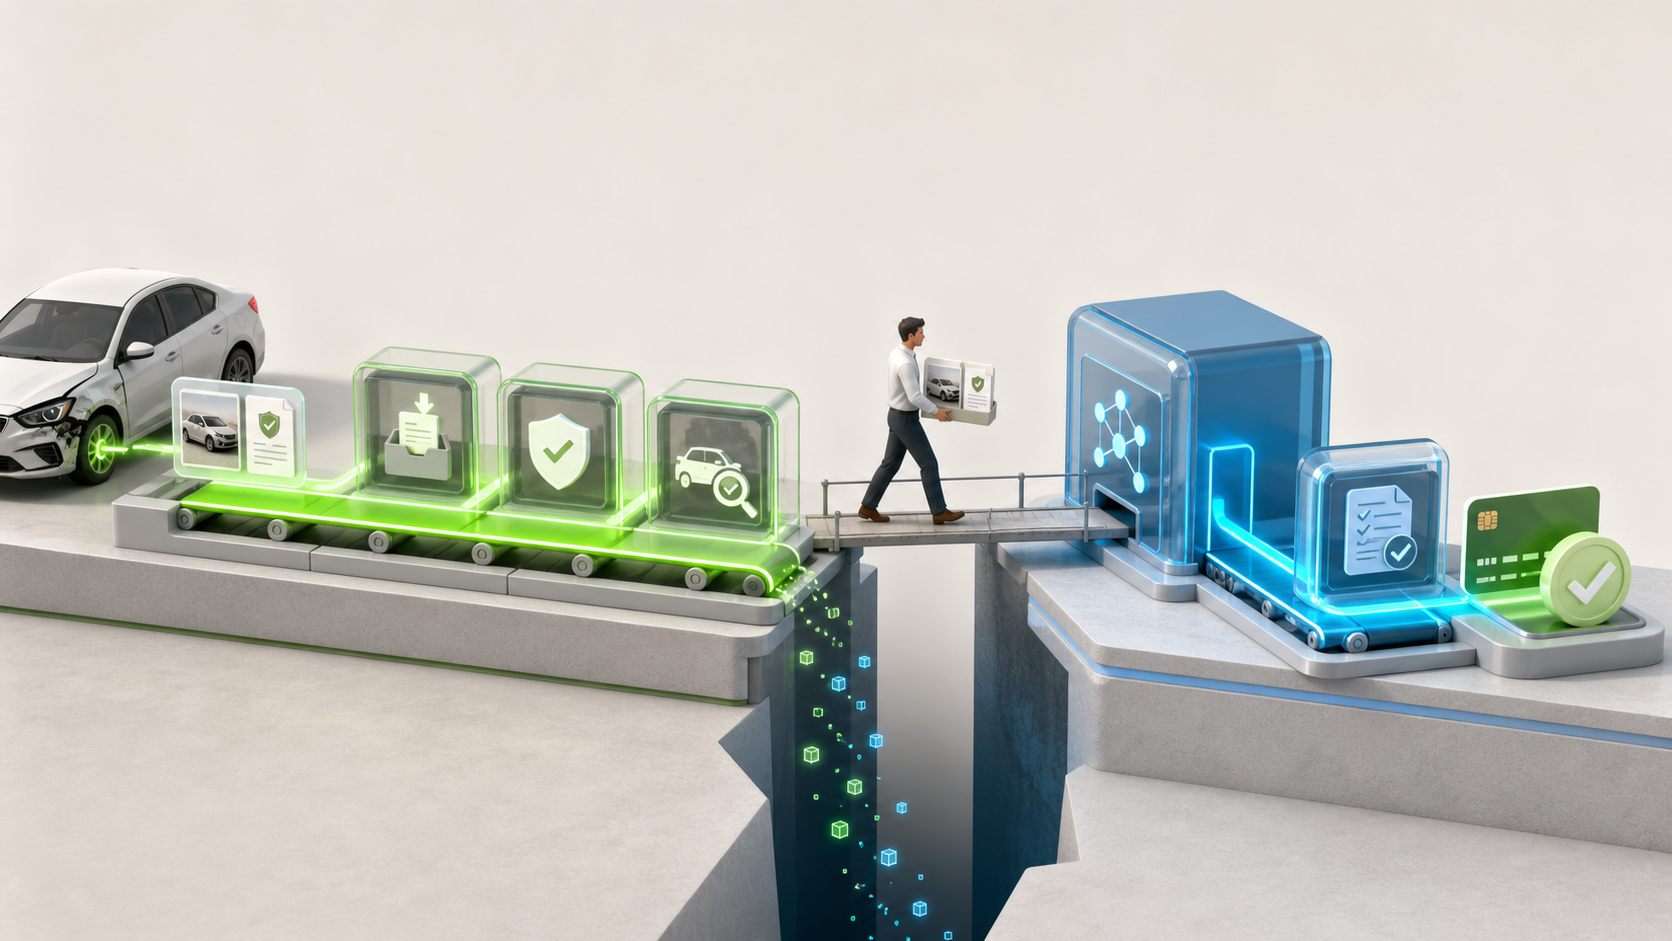
A claim can move through document extraction in seconds and still spend two days waiting for the next team to notice it. This is the operational gap behind many automation programmes. The task performs as designed while the claim continues through a fragmented production environment.
EIOPA’s market survey found that 50% of respondents were already using AI in non-life insurance and 24% in life insurance. Yet only 27 participating insurers used AI across the complete value chain. The report concludes that “the majority of insurers use AI only on selected areas and use cases.”
Faster tasks can leave the claim cycle unchanged
Claims operations rarely run inside one platform. Intake may sit in a portal, policy data in a PAS, evidence in a document repository, fraud checks with a specialist provider, and settlement in a payment system.
Consider a motor claim submitted on Friday afternoon. The form is read automatically, the vehicle images are classified, and the policy is confirmed. On Monday, an adjuster discovers that the repair estimate is stored in another queue and no liability decision has been assigned. The automation completed its work. The claim has barely moved.
Robotic process automation improves data entry, document transfer, coverage checks, and payment initiation. Its effect is limited when the next stage lacks the required data, priority, or accountable owner.
The exception path is the real production environment
Straight-through processing follows known rules with complete data. Live operations contain disputed coverage, inconsistent documents, fraud indicators, vulnerable customers, third-party dependencies, and settlement authority limits.
These cases require judgment and a designed route through the operating model. An exception needs a named owner, relevant evidence, a decision deadline, an escalation rule, and a controlled return to the main workflow. Without that structure, automation increases the speed at which claims enter manual queues.
Human oversight remains practical for decisions affecting coverage, liability, and settlement. EIOPA reports that insurers largely use AI this way, with the system proposing an answer and a person retaining the final decision.
Claims performance is determined between the systems
The clearest use cases appear where volume meets repeated coordination: routing claims by complexity, collecting missing documents, synchronising policy and claim records, escalating stalled cases, supporting fraud review, initiating approved payments, and sending accurate status updates.
A credible baseline measures elapsed time between stages, reopened work, exception age, missing-information requests, and customer contacts caused by unclear status. Customer service automation can reduce those enquiries when updates reflect the underlying workflow.
AI enterprise automation creates measurable value when it controls movement across systems, teams, and decision points, including cases that leave the standard path.